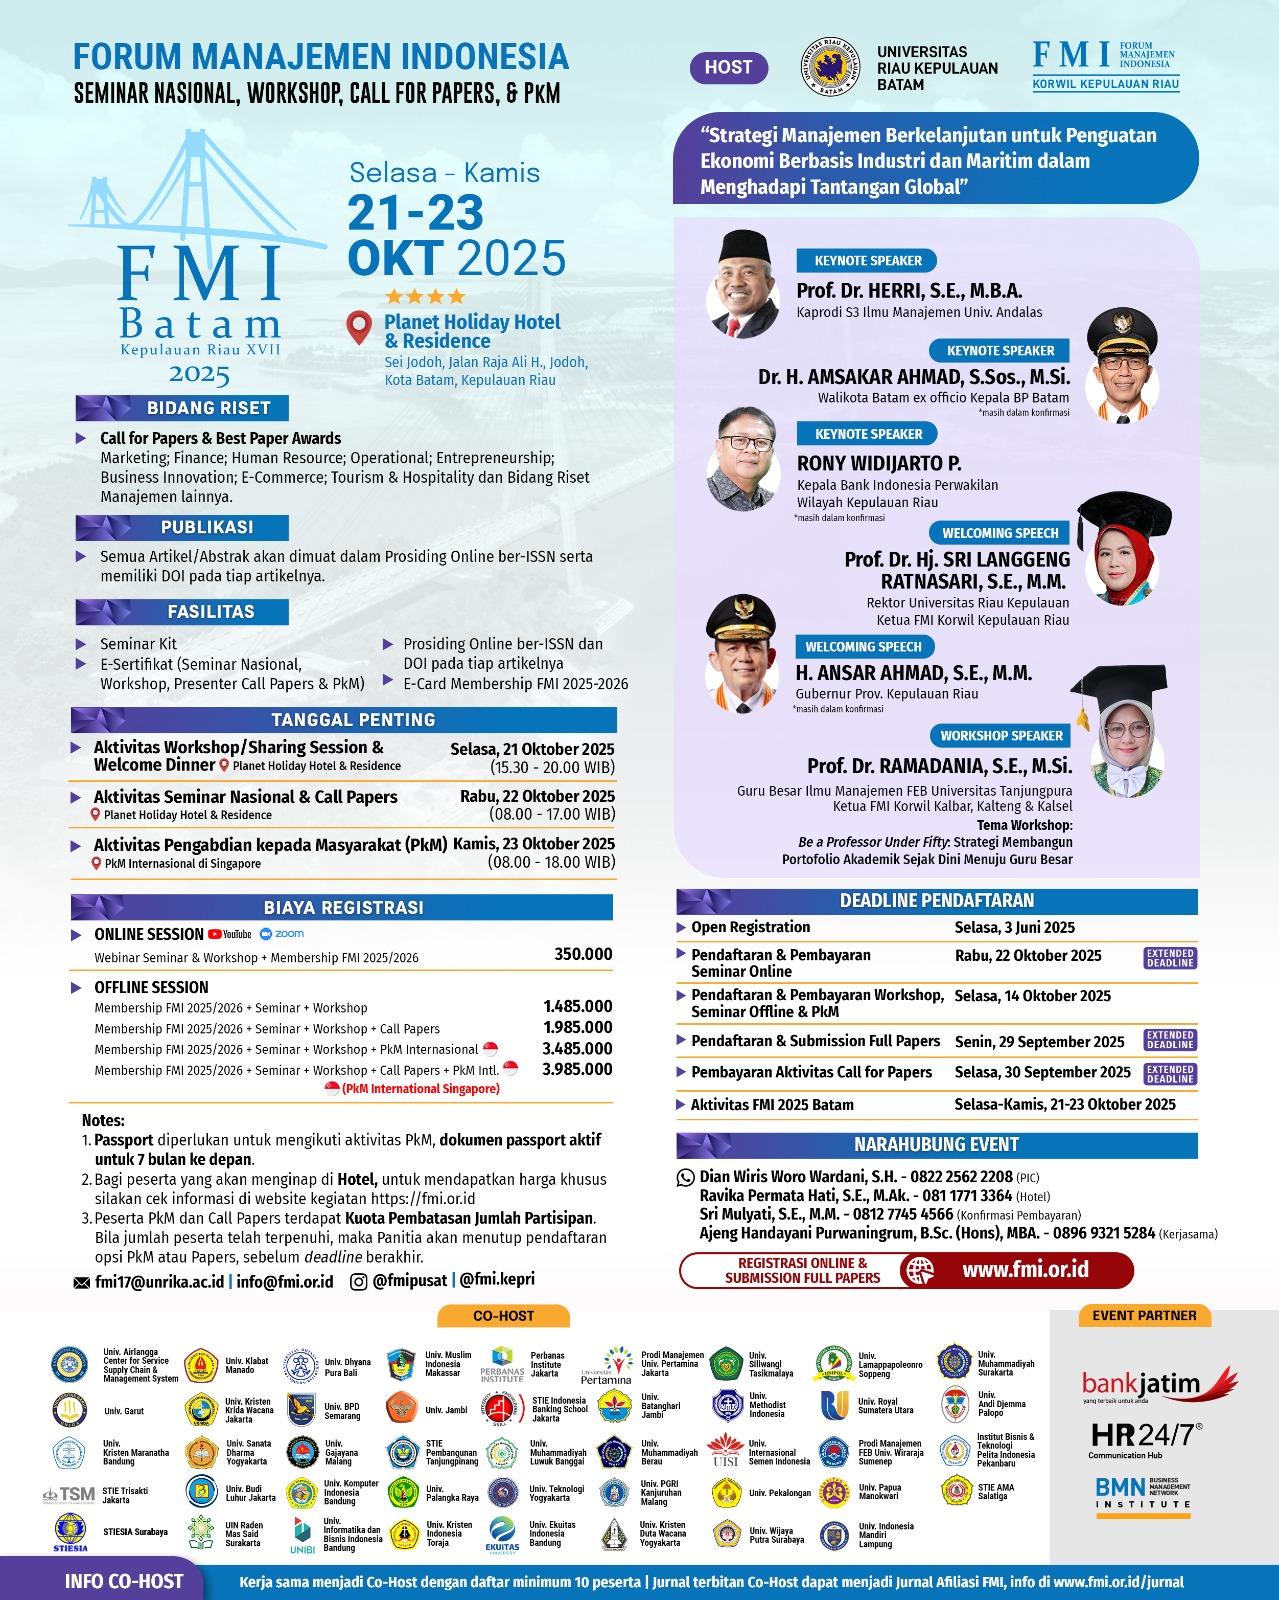
Perilaku Oportunistik Manajerial dan Overvalued Equity: Peran Kepemilikan Manajerial dan Kebijakan Dividen Berkomitmen Pertumbuhan Perusahaan
DOI:
https://doi.org/10.47747/snfmi.v3i1.3158Abstract
This literature review examines the concept of managerial opportunistic behavior from the perspective of agency theory, which is known to be one of the factors contributing to overvalued equity. This condition makes it difficult for companies to return to their original position if left unaddressed. Therefore, companies must understand these factors to avoid bankruptcy. Thus, through this literature review, it is hoped that companies will recognize that managerial opportunistic behavior, as measured by free cash flow, is suspected to be one of the triggers of a decline in company value and ultimately leads to bankruptcy. This study will use two indicators to measure company value —overvalued equity and Tobin's Q — to compare actual company value. Managerial ownership, as a moderating variable, is suspected to strengthen or weaken its influence in causing overvalued equity. This situation must be resolved immediately; therefore, a construct known as the Company's Growth-Committed Dividend Policy is proposed as a mediating variable to overcome overvalued equity. Indeed, the research conducted is still in the form of literature; however, in the future, by using empirical data, it is hoped that it will be possible to prove that the dividend policy committed to company growth is able to overcome the current problems regarding the influence of managerial opportunistic behavior on company value.
References
Amihud, Y., & Lev, B. (1981). Risk reduction as a managerial motive for conglomerate mergers. The Bell Journal of Economics, 12(1), 11–18.
Baker, H. K., & Powell, G. E. (1999). How corporate managers view dividend policy. Quarterly Journal of Business and Economics, 38(2), 17–35.
Bathala, C. T., Moon, K. P., & Rao, R. P. (1994). Managerial ownership, debt policies and the impact of institutional holdings: An agency perspective. Financial Management, 23(3), 38–50.
Bethel, J. E., & Liebeskind, J. (1993). The effect of ownership structure on corporate restructuring. Strategic Management Journal, 14(1), 15–31.
Chen, R., & Steiner, T. (1999). Managerial ownership and agency conflicts: A nonlinear simultaneous equation analysis of managerial ownership, risk taking, debt policy, and dividend policy. Financial Review, 34(2), 22–46.
Crutchley, C. E., & Hansen, R. (1989). A test of agency theory of managerial ownership, corporate leverage, and corporate dividends. Financial Management, 18(4), 35–57.
Darmawan, I. (2006). Pembangunan manusia sebagai sarana pemberdayaan masyarakat miskin. Jurnal Economia, 2(1), 1–11.
DeAngelo, H., & DeAngelo, L. (2000). Controlling stockholders and the disciplinary role of corporate payout policy: A study of the Times Mirror Company. Journal of Financial Economics, 56(2), 153–207.
Dechow, P. M., Richardson, S. A., & Sloan, R. G. (2008). The persistence and pricing of the cash component of earnings. Journal of Accounting Research, 46(3), 537–566.
Demsetz, H., & Lehn, K. (1985). The structure of corporate ownership: Causes and consequences. Journal of Political Economy, 93(6), 1155–1177.
Denis, D. J., Denis, D. K., & Sarin, A. (1994). The information content of dividend changes: Cash flow signaling, overinvestment, and dividend clienteles. Journal of Financial and Quantitative Analysis, 29(4), 567–587.
Easterbrook, F. H. (1984). Two agency-cost explanations of dividends. The American Economic Review, 74(4), 650–659.
Eisenhardt, K. M. (1989). Agency theory: An assessment and review. Academy of Management Review, 14(1), 57–74.
Fairfield, P. M., Whisenant, J. S., & Yohn, T. L. (2003). Accrued earnings and growth: Implications for future profitability and market mispricing. The Accounting Review, 78(1), 353–371.
Ghazali, A. W. (2015). Earnings management: An analysis of opportunistic behaviour, monitoring mechanism and financial distress. Procedia Economics and Finance, 28, 190–201.
Gul, F. A. (2001). Free cash flow, debt-monitoring, and managers’ LIFO/FIFO policy choice. Journal of Corporate Finance, 7(4), 475–492.
Iturriaga, F. J. L., & Sanz, J. A. R. (2000). Ownership structure, corporate value and firm investment: A Spanish firms simultaneous equations analysis. Dirección General de Enseñanza Superior e Investigación Científica.
Jensen, G. R., Solberg, D. P., & Zorn, T. S. (1992). Simultaneous determination of insider ownership, debt, and dividend policies. Journal of Financial and Quantitative Analysis, 27(2), 247–263.
Jensen, M. C. (1986). Agency costs of free cash flow, corporate finance, and takeovers. The American Economic Review, 76(2), 323–329.
Jensen, M. C. (1989). Eclipse of the public corporation. Harvard Business Review, 67(5), 61–74.
Jensen, M. C. (1993). The modern industrial revolution, exit, and the failure of internal control systems. The Journal of Finance, 48(3), 831–880.
Jensen, M. C. (2005). Agency costs of overvalued equity. Financial Management, 34(1), 5–19.
Jensen, M. C., & Meckling, W. H. (1976). Theory of the firm: Managerial behavior, agency costs and ownership structure. Journal of Financial Economics, 3(4), 305–360.
Jensen, M. C., & Murphy, K. J. (1990). CEO incentive: It’s not how much you pay but how. Journal of Applied Corporate Finance, 3(3), 36–49.
Jensen, M. C., & Smith, C. W. Jr. (1994). The modern theory of corporate finance. McGraw–Hill.
Lloyd, W. P., Jahera, J. S. Jr., & Page, D. E. (1985). Agency costs and dividend payout ratios. Quarterly Journal of Business and Economics, 24(3), 19–29.
Mann, S. V., & Sicherman, N. W. (1991). The agency costs of free cash flow: Acquisition activity and equity issues. The Journal of Business, 64(2), 213–227.
Matthew, R., David, T. R., & Viswanathan, S. (2005). Valuation waves and merger activity: The empirical evidence. Journal of Financial Economics, 77(3), 561–603.
McConnell, J. J., & Servaes, H. (1990). Additional evidence on equity ownership and corporate value. Journal of Financial Economics, 27(2), 595–612.
Myers, S. C. (2000). Outside equity. The Journal of Finance, 55(3), 1005–1037.
Myers, S. C., & Majluf, N. S. (1984). Corporate financing and investment decisions when firms have information that investors do not have. Journal of Financial Economics, 13(2), 187–221.
Porta, R. L., Lopez‐de‐Silanes, F., Shleifer, A., & Vishny, R. W. (2000). Agency problems and dividend policies around the world. The Journal of Finance, 55(1), 1–33.
Ross, S. A. (1973). The economic theory of agency: The principal’s problem. The American Economic Review, 63(2), 134–139.
Rozeff, M. S. (1982). Growth, beta, and agency costs as determinants of dividend payout ratios. Journal of Financial Research, 5(3), 249–259.
Sianturi, J. A. T. P. (2020). Penerapan kebijakan dividen berkomitmen pertumbuhan perusahaan dalam profitabilitas dan implikasinya pada nilai perusahaan (Doctoral dissertation). Universitas Diponegoro, Semarang.
Smith, C. W. Jr., & Watts, R. L. (1992). The investment opportunity set and corporate financing, dividend, and compensation policies. Journal of Financial Economics, 32(3), 263–292.
Stulz, R. M. (1988). Managerial control of voting rights, financing policies and the market for corporate control. Journal of Financial Economics, 20(1–2), 25–54.
Stulz, R. M. (1990). Managerial discretion and optimal financing policies. Journal of Financial Economics, 26(1), 3–27.
Titman, S., Wei, K. J., & Xie, F. (2004). Capital investments and stock returns. Journal of Financial and Quantitative Analysis, 39(4), 677–700.
Watts, R. L., & Zimmerman, J. L. (1990). Positive accounting theory: A ten-year perspective. The Accounting Review, 65(1), 131–156.